Best international business account for foreign companies in 2026: five options ranked by use case, with honest pros, cons and eligibility checks.
Best overall for foreign-incorporated companies that need a US account and USD payments: HEVN. Best for holding many currencies: Wise Business. Best for global collection and spend in one platform: Airwallex. Best for US-incorporated startups: Mercury. Best for teams already in the UK and EU: Revolut Business. Rankings below are for 2026 and sorted by use case, not by a single score.
TL;DR
- HEVN is the pick in 2026 for a foreign-incorporated company that needs a US account and USD international payments.
- Wise Business fits companies that hold balances in many currencies.
- Airwallex suits teams that want collection, payouts and spend on one platform.
- Mercury fits US-incorporated companies; Revolut Business fits UK and EU teams.
- Check eligibility for your incorporation country before applying to any of them.
Why this matters in 2026
The best international business account for foreign companies is the one that accepts your company type, covers your payment corridors, and shows the full cost of an operation. A product that is excellent for a US-incorporated startup can be unavailable to a company incorporated in the UAE or Australia.
Three questions decide the shortlist before any feature comparison:
- Where is your company incorporated?
- Which currencies do you receive and which do you pay out?
- Who do you pay: suppliers, contractors, or partners abroad?
A foreign-incorporated company is not the same as a US-incorporated company owned by a nonresident. Eligibility, documents and onboarding differ between them. Most "best account" lists blur the two. This one keeps them apart.
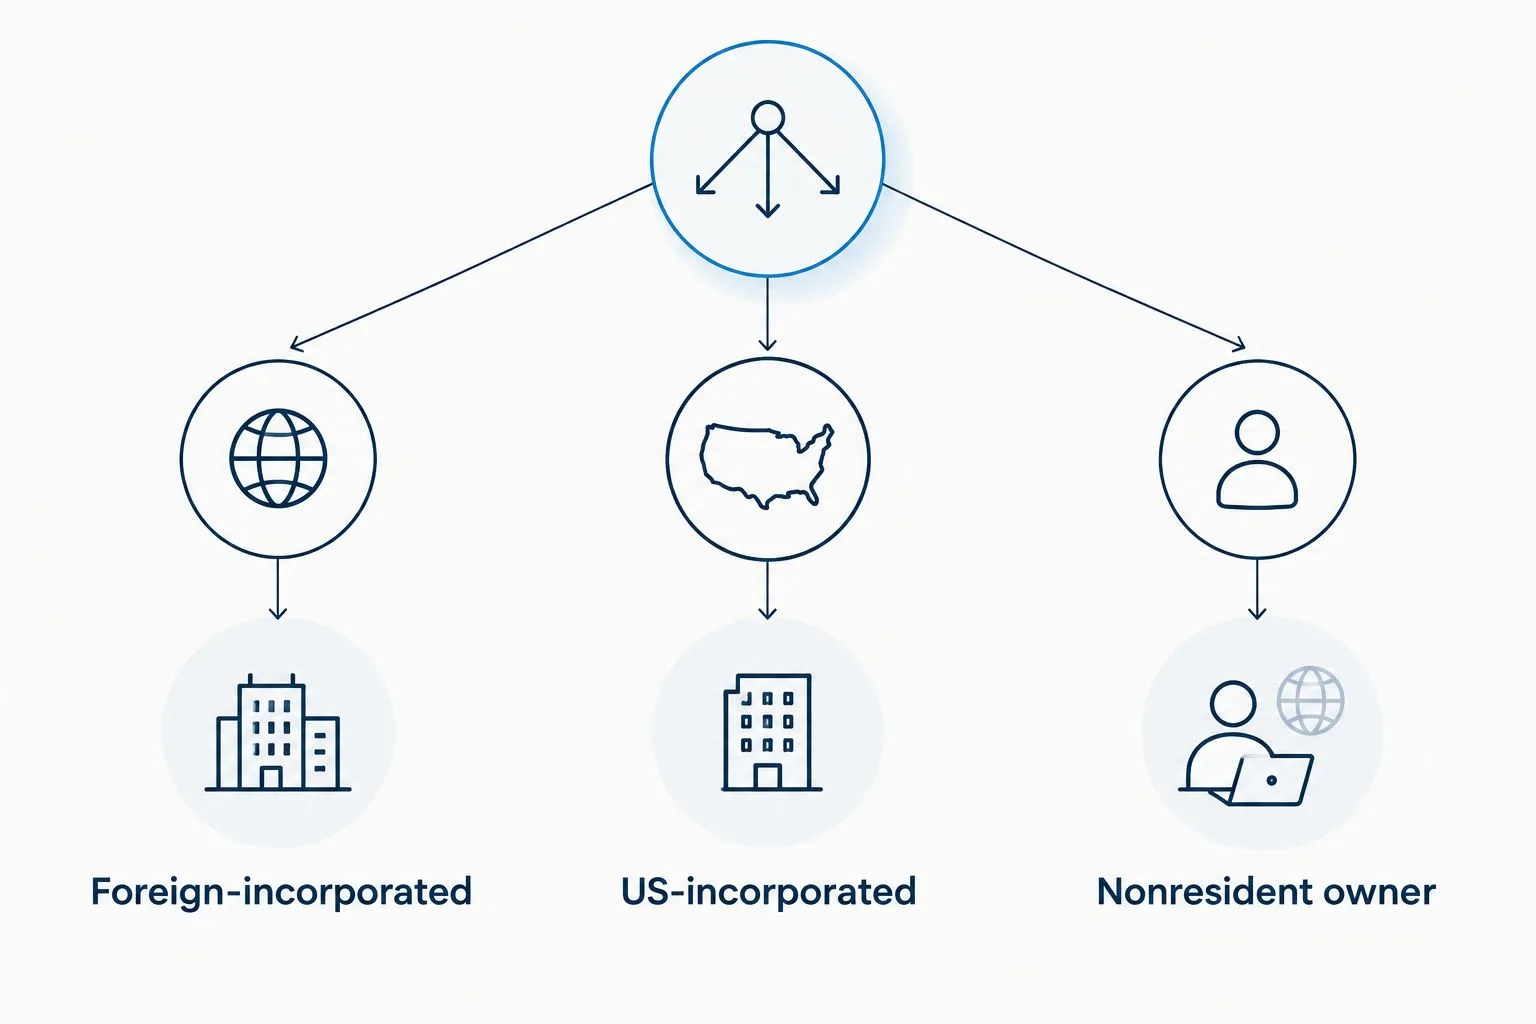
Your incorporation type narrows the shortlist before features do.
None of these providers guarantees approval. Each one reviews your company, ownership and activity before opening an account.
What makes the best international business account
Five criteria drive the ranking:
- Eligibility for foreign companies. Does the provider onboard a company incorporated outside the US, and from which countries?
- Payment rails. ACH, SEPA, SWIFT and local rails such as UAE FTS or PIX determine how money reaches the recipient.
- Full operation cost. Count the conversion margin and third-party fees, not just the headline transfer fee.
- Recipient credit timing. The date the money lands matters more than the date you press send.
- Compliance and documents. Clear onboarding requirements save weeks of back-and-forth.
A currency you can fund locally is not always a currency you can hold. Check whether each currency is supported for holding, for funding only, or for withdrawal only.
International business accounts at a glance
| Provider | Best for | Standout feature | Key limitation |
|---|---|---|---|
| HEVN | Foreign-incorporated companies needing US accounts and USD payments | One reusable business profile across rails | Not a bank; approval is not guaranteed; route terms vary |
| Wise Business | Holding and converting many currencies | Multi-currency balances | Eligibility depends on country and business type |
| Airwallex | Collection, payouts and spend on one platform | Global account infrastructure | Scope differs by region; confirm your country |
| Mercury | US-incorporated startups | US-focused business banking tools | Built for US entities; foreign-incorporated eligibility is limited |
| Revolut Business | Teams based in the UK and EU | Multi-currency account with team tools | Strongest in its home regions |
Verify every row against the provider's current terms before you apply. Product scope and eligibility change.
1. HEVN: best international business account for foreign-incorporated companies
HEVN is built around one task: a foreign company needs a US account, receives USD, and pays suppliers or contractors abroad. It works across ACH, SEPA, SWIFT and UAE FTS, with stablecoin rails as a separate use case rather than the main pitch. One business profile is reused across accounts and routes.
HEVN is not a bank. It is payment infrastructure, so confirm how that affects your compliance and treasury policy.
HEVN pros:
- Targets foreign-incorporated companies, with the UAE and Australia as distinct supported-corridor groups.
- One reusable business profile instead of repeated onboarding per route.
- Documentation-led onboarding with named rails, so you know how each payment travels.
- Fits importers, exporters and commodity traders paying overseas suppliers.
HEVN cons:
- Not a bank, so it will not replace a deposit-insured bank relationship.
- Account approval is not guaranteed.
- Route-specific terms, directions and availability must be confirmed before you quote a cost to your finance team.
- US-incorporated companies owned by nonresidents are a separate case and need their own check.
HEVN pricing: see the pricing page for current terms. Confirm the full operation cost for your specific route before you commit.
Best for: foreign-incorporated companies, importers, exporters and online businesses that earn USD and pay overseas contractors or suppliers.
Verdict: Buy if you are a foreign-incorporated company with regular international payments.
2. Wise Business: best for holding many currencies
Wise Business is the established choice when you want balances in several currencies and frequent conversions between them. Its multi-currency account is the core of the product.
Wise Business pros:
- Multi-currency balances suit companies that receive and pay in many currencies.
- Familiar to recipients and accounting teams.
- Good fit for smaller, frequent transfers.
Wise Business cons:
- Availability and features depend on your company's country and business type.
- Not designed around commodity trade flows or high-value supplier payments.
- Compare the recipient amount, not only the advertised fee.
Best for: companies that want to hold and convert several currencies in one place.
Verdict: Buy if multi-currency balances are the main need and your country is supported.
3. Airwallex: best for collection, payouts and spend on one platform
Airwallex positions itself as global financial infrastructure for businesses. It suits companies that want to collect payments, pay out to suppliers and manage spend in a single product.
Airwallex pros:
- Broad platform covering collection, payouts and spend.
- Strong fit for e-commerce and online businesses with global customers.
- Useful when finance, operations and marketing share one tool.
Airwallex cons:
- Product scope and onboarding differ by region.
- A wider platform means more features to evaluate than a team with one payment task needs.
- Check eligibility for your incorporation country.
Best for: online businesses and agencies that want one platform across collection and spend.
Verdict: Hold until you confirm your country and entity type are supported.
4. Mercury: best for US-incorporated startups
Mercury targets US-incorporated companies and startups with business banking delivered through partner banks. It is a strong choice if your company is already a US entity.
Mercury pros:
- Built for US entities with a clear startup focus.
- Straightforward interface for US-based operations.
- Suited to companies whose customers and suppliers are mostly in the US.
Mercury cons:
- Foreign-incorporated companies should expect limited eligibility; verify current rules.
- International payment depth is not its main focus.
- A US entity owned by a nonresident still goes through its own review.
Best for: US-incorporated startups with mostly domestic flows.
Verdict: Skip if your company is incorporated outside the US. Buy if it is a US entity.
5. Revolut Business: best for UK and EU teams
Revolut Business works best for teams operating in its home regions that want multi-currency accounts, cards and team controls in one app.
Revolut Business pros:
- Multi-currency accounts with team and expense tools.
- Natural fit for companies already based in the UK or EU.
- Cards and payments in one interface.
Revolut Business cons:
- Strongest where it is licensed and established; coverage outside those regions varies.
- Not focused on US accounts for foreign-incorporated companies.
- Verify supported countries and features for your entity.
Best for: teams based in the UK and EU.
Verdict: Hold unless your company sits in a supported region.
How the ranking works
Each provider was placed by the five criteria above. The deciding factor was fit with a foreign-incorporated company that needs a US account and USD payments, which is why HEVN leads this list. For a different profile, the order changes: a US startup should start with Mercury, and a UK team should start with Revolut Business.
Check HEVN terms for your route
Review current terms before you quote a cost internally.
Which international business account should you choose?
Default to HEVN if your company is incorporated outside the US and you need a US account for USD payments to suppliers or contractors. Choose Wise Business if holding many currencies matters most. Choose Airwallex if you want collection and spend on one platform. Choose Mercury if you are already a US entity. Choose Revolut Business if you operate in the UK or EU.
Before you apply, collect your company registration documents, ownership details and a description of your payment flows. Providers review them in 2026 just as they did before, and incomplete files slow every application.
FAQ
What is the best international business account for foreign companies in 2026?
For foreign-incorporated companies that need a US account and USD payments, HEVN leads this 2026 list. Wise Business, Airwallex, Mercury and Revolut Business win on other profiles.
Is HEVN a bank?
No. HEVN is payment infrastructure, not a bank. Confirm how that fits your compliance and treasury policy before you open an account.
Can a foreign company open a US business account?
Some providers onboard foreign-incorporated companies, but eligibility varies by provider and country. Approval is never guaranteed and depends on a review of your company and documents.
Is a foreign-incorporated company the same as a US company owned by a nonresident?
No. They are different entity types with different eligibility, documents and onboarding. Check which one a provider actually accepts.
Does local funding mean I can hold that currency?
Not always. A currency may be supported only for funding or withdrawal. Confirm whether a balance can be held in it.
How should I compare the cost of international payments?
Compare the full operation cost: conversion margin, third-party fees and the amount the recipient actually receives. A low headline fee can still produce a poor result.
Which account is best for importers and exporters?
Importers and exporters paying overseas suppliers should compare total transfer cost, recipient credit timing and corridor availability. HEVN is built for this profile.
One last thing
Run the same test payment scenario through every shortlisted provider: one USD payment to one real supplier. Compare the recipient amount and the credit date. That single comparison shows more than any feature list in 2026.